Personal Financial Statement Before Your First Bank Meeting
Most business owners prepare for their first bank meeting by focusing on their company’s: revenue, EBITDA, cash flow, accounts receivable, growth plans, and the requested credit facility. Those are exactly the issues they should be prepared to discuss. But if a personal guarantee is likely to be part of the financing request, even if you don’t agree that you should be a guarantor, there is another financial statement that deserves attention before the meeting ever takes place.
At some point, the banker is likely to ask, “Can you send me a current Personal Financial Statement?” You’re too late if you think that’s the moment you should start preparing one. Your Personal Financial Statement (PFS) gives the lender important information about the financial strength and obligations of the person standing behind the guarantee, including financial acumen, liquidity, personal leverage, real estate exposure, business interests, outside guarantees, and contingent liabilities.
If you missed our earlier Briefing, Why Strong Companies Hire a Capital Advisor Before Their First Banker Meeting, the principle is straightforward: serious preparation starts before the first lender conversation. Your PFS should be part of that preparation.
Walking into your bank meeting with a current, accurate, and complete PFS signals that you have already reviewed the PFS the bank may use in underwriting. More importantly, you have had the opportunity to identify questions, correct errors, and understand how your financial position is likely to look from the lender’s side of the table before the lender begins evaluating it.
“Your banker should not be the person who tells you it is time to understand your personal financial position. If you expect to personally guarantee a commercial credit facility, know exactly what the lender is going to see before you walk into that first meeting. Preparation changes the conversation.”
- Stacey Huddleston, President & CEO, Green Zone Capital Advisors®
Why This Matters
A Personal Financial Statement can look deceptively simple. List your assets, identify your liabilities, calculate your net worth, sign the document, and send it to the bank. But that is not how a commercial lender evaluates it.
When a bank expects a business owner to personally guarantee a credit facility, the PFS helps underwriting assess the financial strength behind that guarantee. Net worth is part of the analysis, but the number alone does not tell the lender enough. Underwriting also needs to understand what makes up that net worth, how much is liquid, how much is leveraged or encumbered, and what other obligations could compete for the guarantor's financial resources.
A lender may want to understand:
How much liquidity is actually available?
How much of the owner's wealth is tied up in real estate?
How leveraged are those properties?
What other businesses does the owner control?
What obligations from those businesses are personally guaranteed?
Are assets pledged elsewhere?
Are there contingent liabilities that could compete for liquidity?
Are there tax obligations, litigation, judgments, or other financial exposures that require explanation?
This is why two business owners with the same reported net worth can present very different guarantor profiles. An owner showing $10 million of net worth but only $30,000 of accessible liquidity presents a different financial picture than an owner with the same net worth and several million dollars of liquid assets. The same is true when substantial personal wealth is concentrated in leveraged real estate, closely held business interests, or other assets that cannot easily be converted to cash.
That distinction matters in underwriting. The bank is not simply asking, “What is this owner worth?” It is trying to understand the quality and liquidity of the assets supporting that net worth, the obligations already sitting against them, and the financial capacity of the guarantor if the business does not perform as expected.
Preparation Before the Bank Asks
Green Zone® prepares companies for commercial financing by evaluating the financing request the way a bank credit team will evaluate it. We identify likely underwriting questions, determine the appropriate credit structure, prepare lender-ready financial information, and develop the lender strategy before the company enters the market.
That same discipline should apply to the business owner’s Personal Financial Statement. If a personal guarantee is likely to be required, the owner should understand exactly what their PFS says about their liquidity, leverage, outside obligations, business interests, and contingent liabilities before a banker begins reviewing it.
Completing the PFS in advance gives the owner time to confirm asset values and liabilities, identify personally guaranteed obligations, review financial disclosures, and correct incomplete or inconsistent information before it becomes part of the bank’s credit file. It also allows the owner to see the personal financial picture through the same lens the lender will use during underwriting.
This is a basic principle of how Green Zone approaches commercial financing: understand how the bank is likely to evaluate a company before the bank begins its evaluation. Your PFS should be prepared with the same discipline because it signals sophistication to banks and private market lenders.
By the Numbers
Your net worth is only the starting point. A commercial bank underwriter also wants to understand what supports that number and what obligations sit against it.
Liquidity: Cash, deposit accounts, brokerage assets, investments, and retirement funds do not provide the same level of accessibility. A business owner can have substantial net worth while having relatively little cash or other readily available assets. The composition of net worth matters, not just the total.
Real estate: Property values tell only part of the story. Ownership percentages, mortgage balances, monthly payments, and resulting equity provide a clearer measure of the value available to the owner. Reporting $4 million of real estate without identifying the debt against it can materially overstate the strength those assets appear to provide.
Business interests: Ownership in another company may represent significant personal value, but it can also create additional obligations. The value of the ownership interest needs to be considered alongside company debt and any obligations the owner has personally guaranteed.
Contingent liabilities: Not every obligation appears as conventional personal debt. Guarantees, co-borrower obligations, contractual commitments, tax obligations, and other contingent liabilities can create claims against the owner's resources. This becomes especially important when the owner has interests in multiple businesses or real estate entities.
Financial disclosures: Litigation, judgments, bankruptcies, delinquent or disputed taxes, pledged assets, trusts, repossessions, and other financial matters can require additional explanation. Identifying them while preparing the PFS gives the owner time to understand the facts and provide clear, accurate information before questions arise.
Accuracy and completeness: Generic or manually completed PFS forms can create unnecessary problems. Assets may be omitted, liabilities missed, calculations entered incorrectly, or supporting schedules left inconsistent with the summary. Even when the owner's overall finances are strong, incomplete or conflicting information creates questions and slows the review process.
The Green Zone Personal Financial Statement was designed around these realities. Its guided online intake organizes the information commonly requested from a personal guarantor, while the completed PFS presents that information through detailed schedules, asset and liability summaries, calculated net worth, certification, and electronic signature capability.
The purpose is not to make the numbers look better. It is to present the owner's assets, liabilities, liquidity, and obligations accurately and completely in a format that is easier to review and understand. That is what a lender-ready Personal Financial Statement should do.
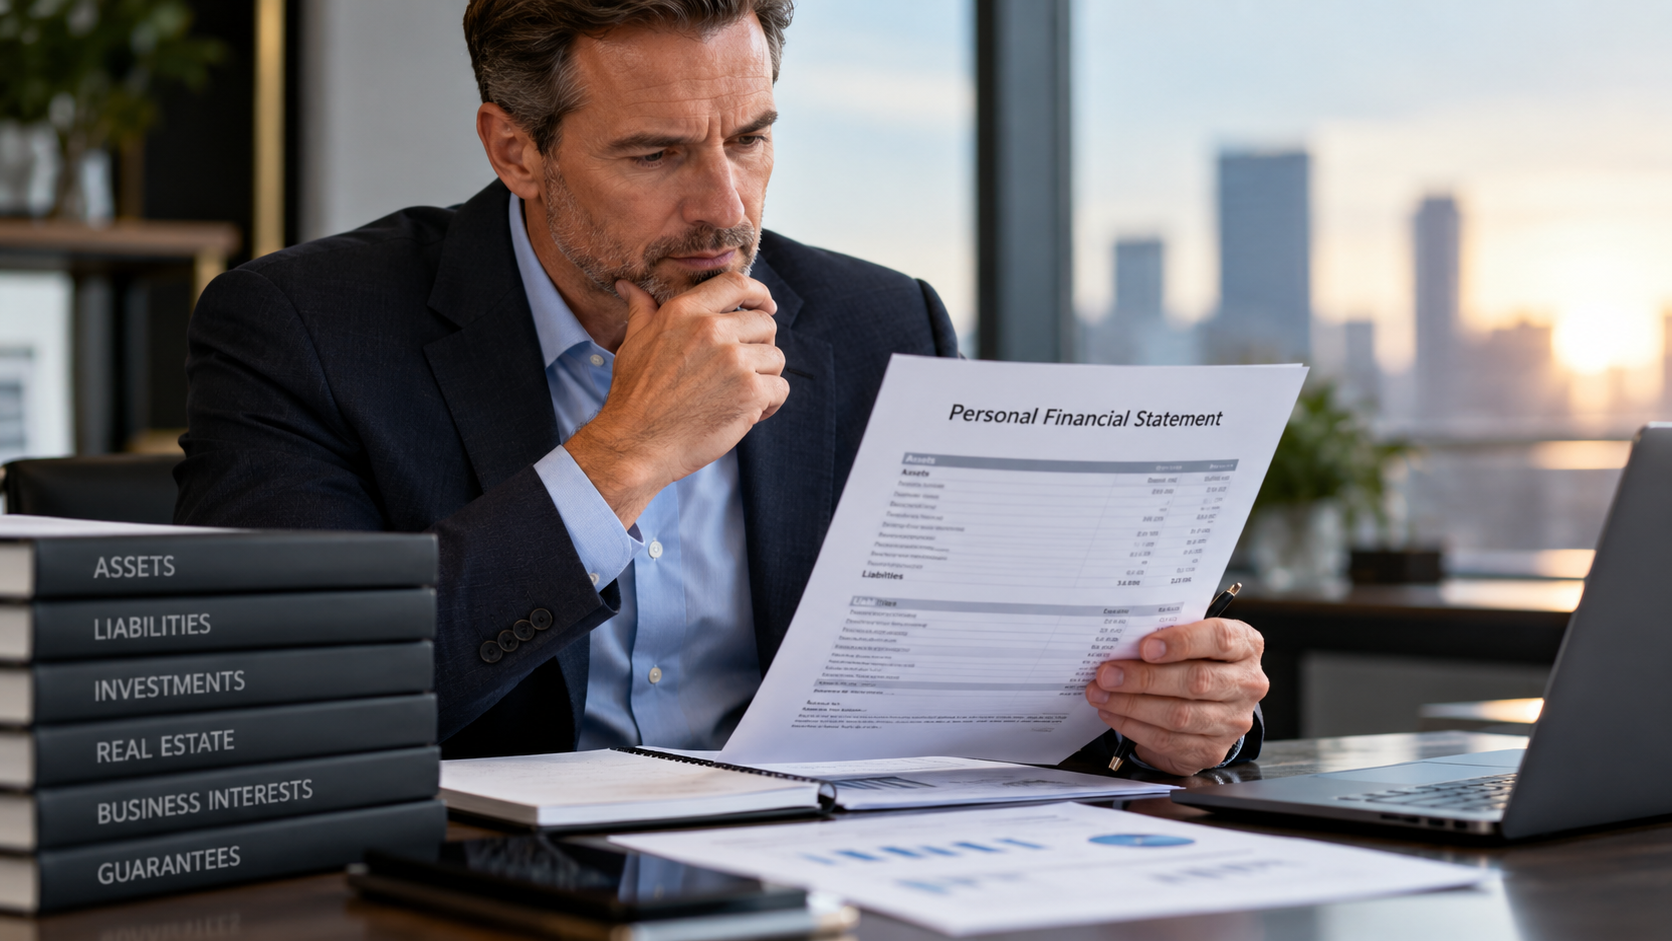
Green Zone Insight
A Personal Financial Statement should not be paperwork you begin because a banker requested it. If a personal guarantee is likely, your PFS should be completed and reviewed ahead of the first serious bank conversation.
1. Know what your net worth is made of. A large net worth does not necessarily mean strong liquidity. Understand how much is held in cash and marketable assets versus retirement accounts, real estate, business interests, and other less-liquid assets.
2. Identify the obligations behind the assets. Review mortgages, investment debt, vehicle loans, personally guaranteed business debt, and other contingent obligations. Gross asset values without the related liabilities can create an incomplete picture.
3. Address questions before the bank raises them. Tax obligations, litigation, pledged assets, trusts, guarantees, and other disclosures should be understood and accurately explained the way a banker can understand in advance. Your PFS should also be consistent with tax returns, debt schedules, real estate schedules, and other information the bank may review.
4. Use the first meeting to discuss the financing request. The conversation should focus on repayment, collateral, credit structure, business performance, and whether the bank is the right fit, not on discovering what information still needs to be assembled.
This is the same preparation discipline Green Zone applies when preparing a business for bank financing and building a strong bank credit memo. Understand what the lender is likely to evaluate before the evaluation begins, and have your answers prepared ahead of time.
When the banker says, “We’ll need a current Personal Financial Statement,” the right answer is simple: “I already have one completed and current. Here you go.”
Why Waiting for the Bank's PFS Can Cost You Time
There is nothing wrong with a bank requiring its own Personal Financial Statement, and some institutions will require their proprietary form regardless of what you provide. The problem is waiting until that form arrives to begin organizing your personal finances.
By then, the financing process is already moving. You may be gathering property values, investment balances, mortgage balances, business interests, personal guarantees, and contingent obligations while simultaneously responding to other lender requests. That creates unnecessary pressure and increases the risk of omissions, inconsistencies, and calculation errors.
Maintaining a current, organized PFS puts you ahead of that process. If the bank accepts your statement, you are ready to provide it. If the bank requires its own form, the information has already been assembled and reviewed, making its completion considerably easier when you copy what you already have to the bank’s form.
Preparing the PFS early can also reveal issues worth understanding before the first meeting. You may discover that substantial net worth is concentrated in illiquid assets, another business carries more personally guaranteed debt than expected, real estate equity is offset by significant debt service, or a financial disclosure requires explanation.
Those are valuable things to know before a lender begins reviewing your information, not after questions start coming back. This also allows you to formulate your answers to expected banker questions.
How Green Zone Wins for You
Green Zone® prepares companies for commercial financing by evaluating the financing request before the bank does. We identify likely underwriting questions, build the lender-ready capital memo, determine the appropriate credit structure, and privately evaluate lender appetite before our client's financial information is broadly distributed.
The Personal Financial Statement extends that same preparation discipline to the guarantor. The company, the financing request, and the business owner should all be ready before lender review begins. If the company is prepared but the owner is not, the financing package is not finished and risks stalling momentum and increasing an underwriter’s negative perception of the owner.